
Why save in Artea
third pillar pension funds?
~40 %
This is the share of your pre-retirement income provided by the Sodra pension.
iki 80 %
This is the share of your pre-retirement income you may receive in retirement if you save in both second and third pillar pension funds.
30+ m.
This is how much investment and asset management experience we have.
40 %
This is the share of Lithuania’s third pillar pension fund assets that we manage.
Contributions – on your terms
You, your family members or your employer can make contributions to your third pillar pension fund account.
Flexible payments
You can choose the payment option that suits you best. The accumulated funds are inheritable.
As many agreements as you need
You can conclude one, two or several pension accumulation agreements for different funds.
Time is on your side
The longer you invest, the more you may expect to accumulate.
Important: the outcome of saving depends on the duration of saving, the contribution amounts, the performance of the selected pension funds and other relevant circumstances.
Do you know what to expect in retirement?
Use our calculator to assess how saving in the third pillar may affect your financial future.

Which third pillar pension
fund is right for you?
When choosing a fund, your age group and the time left until retirement are a useful starting point.

Aged under 47
The more time you have until retirement, the more boldly you can invest. That is why equities may account for up to 100% of your portfolio in these funds.

Aged 47–58
This is the time to balance growth with stability. Equities account for up to 70% of the portfolio in this fund.

Aged 58–65
Retirement is getting closer, so the priority is to preserve what you have already accumulated. This fund invests in bonds or other conservative asset classes.
Artea third pillar pension funds: how do they differ?
You can conclude one, two or several pension accumulation agreements for different funds. Below are the key features to help you choose.
| Ambitious 16+ | Ambitious Index 16+ | Ambitious Active 16+ | Balanced 47+ | Stable 58+ | |
|---|---|---|---|---|---|
| When to choose? | If you want to save in our most popular fund, which combines both passive and active investing. | If you prefer passive investing in a global equity portfolio. | If you believe in active fund management. | If you are looking for a solution with a balanced equity and bond portfolio. | If you are approaching retirement age and/or prefer a low level of investment risk. |
| Strategy | Index Plus | Passive | Active | Index Plus | Index Plus |
| Equity share | Up to 100 % | Up to 100 % | Up to 100 % | 50–70 % | 0 % |
| Sustainability – share of sustainable investments* | At least 50 % | At least 80 % | At least 50 % | At least 50 % | At least 50 % |
| Target share of actively managed investments by fund managers | About 30 % | None | About 50 % | About 50 % | About 90 % |
| Investment fluctuations and expected return | Highest | Highest | Highest | Medium | Lowest |
| Management fee | 0,8 % | 0,59 % | 1,5 % | 0,8 % | 1,0 % |
| Entry fee** | 30 %. Not applicable to a single contribution of EUR 1,500 or more. | 30%. Not applicable to a single contribution of EUR 1,500 or more. | Not applicable. | 30%. Not applicable to a single contribution of EUR 1,500 or more. | Not applicable. |
| Geographical distribution of investments | North America, Western Europe, Asia and Oceania, the Baltic States, the Middle East and Africa | North America, Asia and Oceania, Western Europe, the Middle East and Africa, South and Central America | North America, Western Europe, Central and Eastern Europe, the Baltic States, Asia and Oceania | North America, Central and Eastern Europe, Western Europe and the Baltic States, Asia and Oceania | The Baltic States, Central and Eastern Europe, Western Europe, Central and South America, other countries |
* Share of investments in the fund’s portfolio aligned with responsible environmental, social and governance (ESG) principles.
** A discount may apply to employer contributions. All fees and their application are disclosed in the pension fund rules.
Third Pillar Pension Fund Performance
Review the returns of third pillar pension funds and compare the performance of different funds.

How to start saving in a
third pillar pension fund?
Choose based on your age or the level of risk you are comfortable with. If you find it difficult to decide, let's talk. The consultation is free of charge.
Online via the Pension self-service portal, using Smart-ID / Mobile-ID, or at any Artea Bank branch.
Regular contributions can help you grow your savings more consistently and spread investment risk more evenly over time.
It is suggested that you aim to save 10–15% of your monthly income, taking into account your goals and financial capacity.
Third pillar pension payment options:
which can you choose?
One-off benefit
You can withdraw all the funds accumulated in the third pillar at once as a one-off benefit.
Periodic payments
You will receive regular payments from the pension fund, while the remaining funds will continue to be invested.
Annuity
You will receive regular payments for the rest of your life.
You can withdraw the accumulated funds free of personal income tax (PIT) if you have less than 5 years left until retirement age and have been saving for more than 5 years.
accumulate more in the third pillar
The longer you invest, the greater the likelihood of accumulating more. One of the main reasons for this is the compound interest effect. It occurs when returns are earned not only on the funds you have invested, but also on previously earned returns.
Although financial markets may fluctuate in the short term, over a longer period these fluctuations often have less impact on the final outcome. Long-term investing therefore provides more opportunities to benefit from market growth and accumulate a higher investment return.
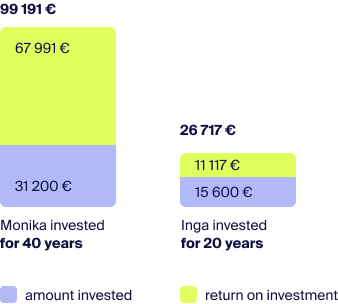
This is well illustrated by the example of two customers.
Inga invested for 20 years, and during this period each euro she invested earned an additional EUR 0.71. Monika, meanwhile, invested for 40 years, so each euro she invested generated as much as EUR 2.18 in additional return.
This example shows that time is one of an investor’s most important allies – the longer you invest, the stronger the compound interest effect becomes and the greater the amount you may accumulate.
How long should you save for retirement?
The amount you save will depend on when you start investing.
Important to know: investing involves risk. Past performance does not guarantee the same results in the future. The calculations provided were made using the Moneysmart calculator and are based on theoretical models and the assumptions used in those models. They are for illustrative purposes only and should not be regarded as a reliable indicator of future performance.
The calculations assume monthly investments of EUR 65 and an average annual investment return of 5% after applicable fees.
PIT – personal income tax.
Although you can make contributions to a third pillar pension fund at any time and in any amount, regular saving can help your accumulated funds grow faster and increase the overall value of your assets for the future.
To make saving even easier, you can use the e-invoice service.
Set a contribution amount and payment date that suit you, for example, immediately after receiving your salary. Your contributions will then be transferred automatically, so you will not have to worry about making regular transfers or forgetting them.
More and more companies are focusing on their employees’ financial well-being and offering employer-funded retirement saving as an additional benefit. This can be a valuable way to save for the future using not only your own funds, but also contributions provided by your employer.
If your employer does not yet offer this option, you can initiate a conversation about additional workplace retirement saving yourself.
To learn more about this option and its benefits, visit the Artea Bank customer service branch that is most convenient for you – we will provide detailed information and answer any questions you may have.
Log in to the Pension self-service portal – there you will always find up-to-date information about your third pillar pension savings and messages intended for you. You will also be able to check whether your current contributions are likely to help you accumulate the amount you want for the future.
When assessing your accumulated assets, remember that financial markets are subject to fluctuations. If a fund’s return becomes negative over a certain period, long-term saving can often help reduce the impact of short-term market movements on the final outcome.
If you have any questions or would like advice about your pension savings, contact us – we will be happy to help and answer any questions you may have.
Sign a contract
now!

Sign a contract
Sign a third-pillar pension accumulation contract online.

Have questions?
Fill out the form and we will contact you.

Let’s talk
A free customer service line is available daily from 8:00 AM to 8:00 PM.
Frequently Asked Questions
Both second pillar and third pillar pension funds are part of the same long-term pension saving system.
The third pension pillar is attractive because of its flexibility – you can save in several funds at the same time. You decide how much to contribute and when to make contributions. Contributions can be made by you, your employer or a family member. All accumulated funds are inheritable.
The accumulated funds can be withdrawn at any time. However, it is important to note that personal income tax (PIT) applies if you have participated in a third pillar pension fund for less than 5 years or have more than 5 years remaining until retirement. If you concluded the agreement by the end of 2024, a personal income tax (PIT) relief applies to third pillar contributions.
When saving in third pillar pension funds, there is no defined obligation to make contributions of a certain amount, so you can choose the amount, frequency and regularity of your contributions yourself.
We recommend making contributions regularly, on a monthly basis, to reduce the impact of market fluctuation risk. As a guideline for determining the contribution amount, we recommend dividing your age in years by two and treating the resulting figure as the percentage of your income to set aside for long-term saving.
The third pillar pension funds managed by UAB Artea Asset Management differ in their investment focus and risk-return ratio. The pension funds are managed based on the life-cycle concept, meaning that saving is most effective when the pension fund is changed at certain stages over time in order to reduce investment risk. Choose pension funds that correspond to your age.
Are you 16–46 years old?
The Artea Ambitious 16+, Artea Ambitious Active 16+ and Artea Ambitious Index 16+ funds may be suitable for you.
We recommend choosing pension funds in which equities account for up to 100% of investments. Equity prices fluctuate, which may result in losses over the short term. Such fluctuations reflect the higher short-term volatility risk of these funds, while over the long term investments are generally profitable.
Are you 47–57 years old?
The Artea Balanced 47+ fund may be suitable for you.
We recommend choosing pension funds in which up to 50% is invested in equity markets, with the remainder invested in bonds and term deposits. The value of these funds fluctuates less in the short term, which reflects a lower risk of changes in fund value, but their profitability is also lower than that of equity funds.
Are you 58 or older?
The Artea Stable 58+ fund may be suitable for you.
We recommend choosing a pension fund in which 100% of the assets are invested in the lowest-risk securities, bonds and term deposits. This stage is referred to as a capital preservation strategy – investment returns are low, but so is the risk of fluctuations.
You can find a comparison of all Artea Ambitious funds here.
For agreements concluded and entered into force by 31 December 2024, personal income tax (PIT) relief applies and will continue to apply for another 10 years, i.e. until 1 January 2035.
Funds can be withdrawn from a third pillar pension fund at any time. However, personal income tax (PIT) may apply if the funds are withdrawn before reaching retirement age.
If you save for an additional pension until retirement age, or until no more than 5 years before reaching retirement age, have been saving for at least 5 years and have used the PIT relief, payments from your third pillar pension fund account will not be subject to tax.
| Client age |
Up to age 55 |
Age 55, but more than 5 years until retirement |
5 years until retirement; retirement age; assessed work capacity level of 0–40% |
5 years until retirement; retirement age; assessed work capacity level of 0–40% |
|
|---|---|---|---|---|---|
| Period of participation under the agreement | Not applicable | Agreement concluded by 31 December 2012 | 5 years or more | Less than 5 years | |
| Used PIT relief and/or employer made contributions | Amount of benefit equal to the contributions made | 15 % | 0 % | 0 % | 15 % |
| Amount of benefit exceeding the contributions made (investment return) | 15 % | 0 % | 0 % | 15 % | |
| Did not use PIT relief and no employer contributions were made | Amount of benefit equal to the contributions made | 0 % | 0 % | 0 % | 0 % |
| Amount of benefit exceeding the contributions made (investment return) | 15 % | 0 % | 0 % | 15 % | |
Yes, both assets being accumulated and assets already accumulated in the third pillar are inheritable.
It is simple. You can use the prepared instructions.
It is advisable to start saving and investing as early as possible, because the longer the investment period, the smaller the share of your income you will need to allocate to investing.
The aim is for income in retirement to amount to around 70% of your pre-retirement earnings.
You may also be
interested in
Deposits
Artea offers some of the highest interest rates among the banks in the country.
Advanced securities trading platform
Invest into shares in the Baltic States and worldwide.
Investment funds
Invest in a diverse range of funds to maximize your company’s financial returns.
Second pillar pension
Pension accumulation in funds, allowing you to accumulate up to 20-30% of your former earnings for your pension.
Important to know: when participating in a third pillar pension fund, you will pay the fees set out in the rules of the selected pension fund. Your funds will be invested in accordance with the investment strategy of the selected fund. By saving in pension funds, you assume investment risk and other investment-related risks, which means that the value of investments may rise or fall and you may get back less than you invested.
The value of a pension fund unit may fluctuate, and the fund’s past performance does not guarantee the same results or profitability in the future. Past performance is not a reliable indicator of future performance. Before making a decision, carefully assess all investment risks, either independently or in consultation with an investment adviser. Please read the pension fund rules, which form an integral part of the pension accumulation agreement.
All information presented is of a promotional nature and may not be interpreted as a recommendation, offer or invitation to save in pension funds managed by Artea Asset Management, the asset management company of the Artea Bank Group. Although the information has been prepared on the basis of sources believed to be reliable, Artea Bank and Artea Asset Management are not liable for any inaccuracies or losses you may incur as a result of relying on this information.